
Domestic Substitution Space for Advanced Packaging Materials (Underfill/TIM)
As advanced packaging and heterogeneous integration move from niche capabilities to mainstream semiconductor strategy, materials that once lived quietly in the background are suddenly in the spotlight. Underfill and thermal interface materials, or TIMs, are especially important. They are not glamorous, and they rarely make headlines, but they influence yield, reliability, and thermal performance in some of the most demanding packages being built today. That is why the domestic substitution space for these materials is becoming such a major topic.
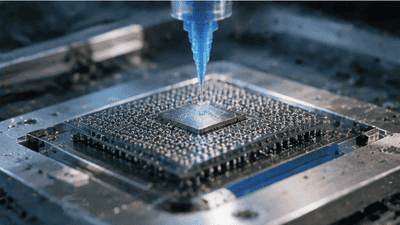
In simple terms, the market is asking a bigger question: can domestic suppliers replace imported advanced packaging materials without sacrificing performance? The answer is not binary. Some applications are already ready for localization. Others still require more qualification, more process tuning, and more confidence from customers. But the direction is clear. As packaging gets more complex, the value of reliable local supply rises, and underfill and TIM are increasingly viewed as strategic materials rather than commodity consumables.
Why Underfill and TIM Matter So Much
Underfill and TIM play very different roles, but they are equally critical. Underfill is used to support mechanical reliability in flip-chip and advanced packaging structures, especially where fine-pitch bumps or direct connections are exposed to thermal and mechanical stress. TIM, by contrast, helps move heat from the chip or lid into the thermal management system. In advanced packaging, both materials are essential because the package must be both mechanically stable and thermally efficient.
The reason these materials matter more now is that advanced packaging has raised the stakes. A package may include multiple dies, HBM stacks, interposers, and thin substrates. That creates more stress, more heat, and more sensitivity to material behavior. Underfill has to cushion and protect. TIM has to conduct heat without creating voids or adding excessive resistance. If either one underperforms, the entire module may suffer.
This makes domestic substitution more than a procurement issue. It is a performance issue. A replacement material must not only exist locally; it must work in high-value packages where reliability and thermal control are non-negotiable.
What Advanced Packaging Demands from Materials
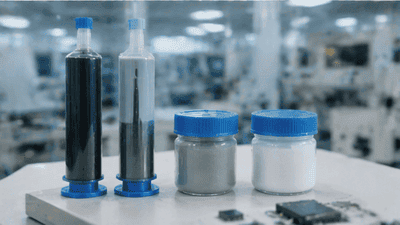
Advanced packaging and heterogeneous integration impose a set of unusually difficult requirements on materials. Underfill and TIM must now work in environments that are tighter, hotter, thinner, and more mechanically sensitive than before. That means the material properties that matter most include:
- Thermal conductivity.
- Coefficient of thermal expansion compatibility.
- Low voiding and strong adhesion.
- Moisture resistance.
- Processability during dispensing, curing, or bonding.
A material that looked acceptable in older packaging may fail in a chiplet or 3D stack simply because the packaging environment is much harsher. For example, a TIM with good thermal performance but poor void control may cause local hotspots. An underfill with good mechanical support but poor flow may create assembly defects. The bar is higher now, and that raises the threshold for domestic substitution.
The Domestic Opportunity
There is still substantial room for domestic replacement in advanced packaging materials. The opportunity exists because the demand is growing quickly, the supply chain is under pressure, and many customers want more resilient sourcing. Advanced packaging materials are no longer a small side business. They are part of a fast-expanding market tied to AI, data centers, automotive electronics, mobile devices, and chiplet-based system integration.
Domestic suppliers can benefit from several trends:
- Increased demand for localized supply chain resilience.
- Growing packaging volumes in consumer, industrial, and automotive markets.
- More opportunities to co-develop materials with local OSATs and foundries.
- A greater willingness from customers to qualify alternatives as long as performance is proven.
In some segments, especially mainstream underfill and standard TIM formulations, localization space is relatively broad. In more advanced and specialized areas, such as high-thermal-conductivity TIMs for AI packages or ultra-low-stress underfills for fine-pitch 3D integration, the substitution path is narrower but still meaningful.
Underfill: The Mechanical Guardian
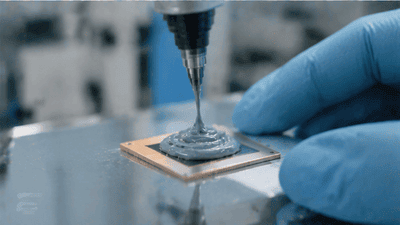
Underfill is one of the most important materials in advanced packaging because it absorbs stress and improves the long-term reliability of solder joints or fine interconnects. As packages get larger and interconnect pitch gets smaller, the need for underfill becomes even more urgent. It helps protect the package from cracking, fatigue, and delamination caused by thermal cycling and mechanical movement.
For domestic substitution, underfill has a few distinct submarkets:
- Capillary underfill for flip-chip and chiplet packages.
- Molded underfill or no-flow underfill for higher integration platforms.
- Advanced formulations for 2.5D and 3D structures.
The more advanced the package, the more demanding the underfill specification. Low viscosity is needed for flow into small gaps. Strong adhesion is needed to prevent interface failure. Thermal stability is essential to handle repeated heating and cooling. And for some applications, electrical properties matter too. This is where domestic suppliers can start with the broad market and move upward gradually into more difficult formulations.
A practical substitution strategy usually begins with applications where the risk of failure is lower and the qualification path is clearer. Over time, as process expertise and materials chemistry improve, suppliers can move into more demanding chiplet and heterogeneous integration use cases.
TIM: The Heat Transfer Bottleneck
TIM, or thermal interface material, has become just as important as underfill in the age of AI and high-performance computing. The reason is simple: power density is rising fast. The more functionality packed into a single module, the harder it becomes to remove heat efficiently. TIM sits between the chip and the lid or heat spreader, and its job is to minimize thermal resistance at that interface.
For domestic substitution, TIM may actually have one of the clearest opportunities because the market is expanding and thermal management is now a top priority in advanced packaging. AI chips, large CPUs, and dense heterogeneous modules all need better heat transfer. A domestic TIM supplier that can deliver high conductivity, low voiding, and good pump-out resistance has a real chance to win business.
That said, TIM is also a highly sensitive material. It has to perform under pressure, stay stable over time, and maintain contact quality through thermal cycling. A TIM that looks great in a lab sample may behave differently in a real package with different surface roughness, lid geometry, or assembly conditions. This is why qualification matters so much.
What Limits Substitution
The domestic substitution space is real, but it is not unlimited. Several constraints remain:
- Performance gaps. Imported materials may still lead in thermal conductivity, consistency, or reliability under extreme conditions.
- Qualification time. Advanced packaging customers are cautious, and material substitution often requires long test cycles.
- Process integration. A material may work chemically but still fail in the actual manufacturing flow.
- Customer trust. High-value AI and automotive packages leave little room for uncertainty.
These limits do not eliminate the substitution opportunity. They simply mean the path is staged. First comes mainstream adoption. Then comes high-volume advanced packaging. Then comes the more difficult frontier of top-end AI and 3D integration. The key is to understand that substitution is not a single event; it is a ladder.
Where Domestic Suppliers Can Win First
The first wins are likely to come in package types where the requirements are strong but not extreme. That includes mainstream flip-chip packaging, mobile and consumer modules, some automotive packages, and system-in-package designs with moderate thermal and mechanical stress. In these applications, domestic underfill and TIM can build track records, collect reliability data, and establish trust.
The next layer of opportunity lies in more advanced heterogeneous integration flows where customers are actively looking for alternate sources. If a local supplier can co-develop a material with an OSAT or foundry and prove stable performance, it can gain a strong foothold. This is especially true where supply chain security matters and customers value having a regional alternative.
The hardest, but perhaps most strategically important, wins are in AI and HPC packages. These products demand the highest thermal conductivity, the lowest voiding, and the most consistent performance under severe operating conditions. Domestic suppliers that can eventually meet those standards could capture very valuable business.
Why Co-Development Matters
One of the biggest lessons in advanced packaging materials is that co-development matters more than pure catalog performance. A material is not adopted because it looks good on a datasheet alone. It is adopted because it works inside a specific package, with a specific process, under a specific reliability target.
That means domestic suppliers need close collaboration with:
- OSATs that understand packaging process windows.
- Foundries that set advanced packaging requirements.
- Chip designers that know thermal and mechanical constraints.
- Equipment vendors that influence curing, dispensing, and assembly behavior.
This co-development loop is powerful because it shortens the path from material idea to commercial qualification. It also helps domestic suppliers build products that fit local manufacturing realities, rather than copying a foreign material without adapting it to the process environment.
Reliability Is the Real Gatekeeper
In advanced packaging, reliability is the final judge. A material can pass initial thermal or mechanical tests and still fail after long-term cycling, humidity exposure, or field use. This is why underfill and TIM qualification can take so long. Customers want confidence that the material will last as long as the package itself.
Reliability testing typically examines:
- Thermal cycling and shock resistance.
- Moisture sensitivity.
- Adhesion strength and delamination behavior.
- Long-term thermal stability and pump-out resistance.
This is where domestic suppliers must prove not just equivalent performance, but consistent performance. Semiconductor customers are often willing to switch suppliers if the new material is good enough and stable enough. They are much less willing to switch if lot-to-lot variation is high or process windows are narrow.
Market Structure and Strategic Value
The market for underfill and TIM is attractive because it sits inside a much larger wave of advanced packaging growth. As heterogeneous integration expands, so does the need for these materials. That creates a structural tailwind for suppliers that can serve the market well. It also gives domestic suppliers a reason to invest in chemistry, reliability labs, and application engineering.
The strategic value is even higher because these materials affect supply chain security. If a package depends on imported underfill or TIM and those materials are disrupted, the whole downstream chain is affected. Local sourcing reduces that risk. In an era where packaging is increasingly central to national semiconductor strategy, that matters a great deal.
What the Next Few Years May Look Like
Over the next few years, the domestic substitution space is likely to expand in waves. First, more local suppliers will enter or strengthen their position in mainstream underfill and TIM. Then, some will move into more advanced package types as they accumulate qualification data. Eventually, the most capable players may begin challenging imported materials in the most demanding AI and 3D integration flows.
The pace of progress will depend on three things:
- How quickly domestic materials science closes the performance gap.
- How effectively suppliers collaborate with packaging customers.
- How much customers value resilience and local supply as part of the sourcing decision.
There is no reason to expect a single overnight breakthrough. But there is every reason to expect steady expansion. In advanced packaging, incremental material improvements can be very valuable, especially when they are paired with strong process support and reliability data.
Conclusion
Domestic substitution space for advanced packaging materials such as underfill and TIM is real, growing, and strategically important. As advanced packaging and heterogeneous integration become central to AI, mobile, automotive, and data center systems, the demand for reliable, high-performance materials keeps rising. Domestic suppliers have a meaningful opportunity to capture more of this market, especially where local supply chain resilience, co-development, and cost-effective qualification matter.
The path is not simple. Performance, reliability, and process integration still set a high bar. But the direction is clear. Underfill and TIM are no longer just supporting materials. They are enablers of the next generation of packaging, and that makes them a valuable arena for domestic capability building. For companies that can combine chemistry, application know-how, and customer trust, the substitution space is wide enough to matter and deep enough to reward serious investment.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?